Description
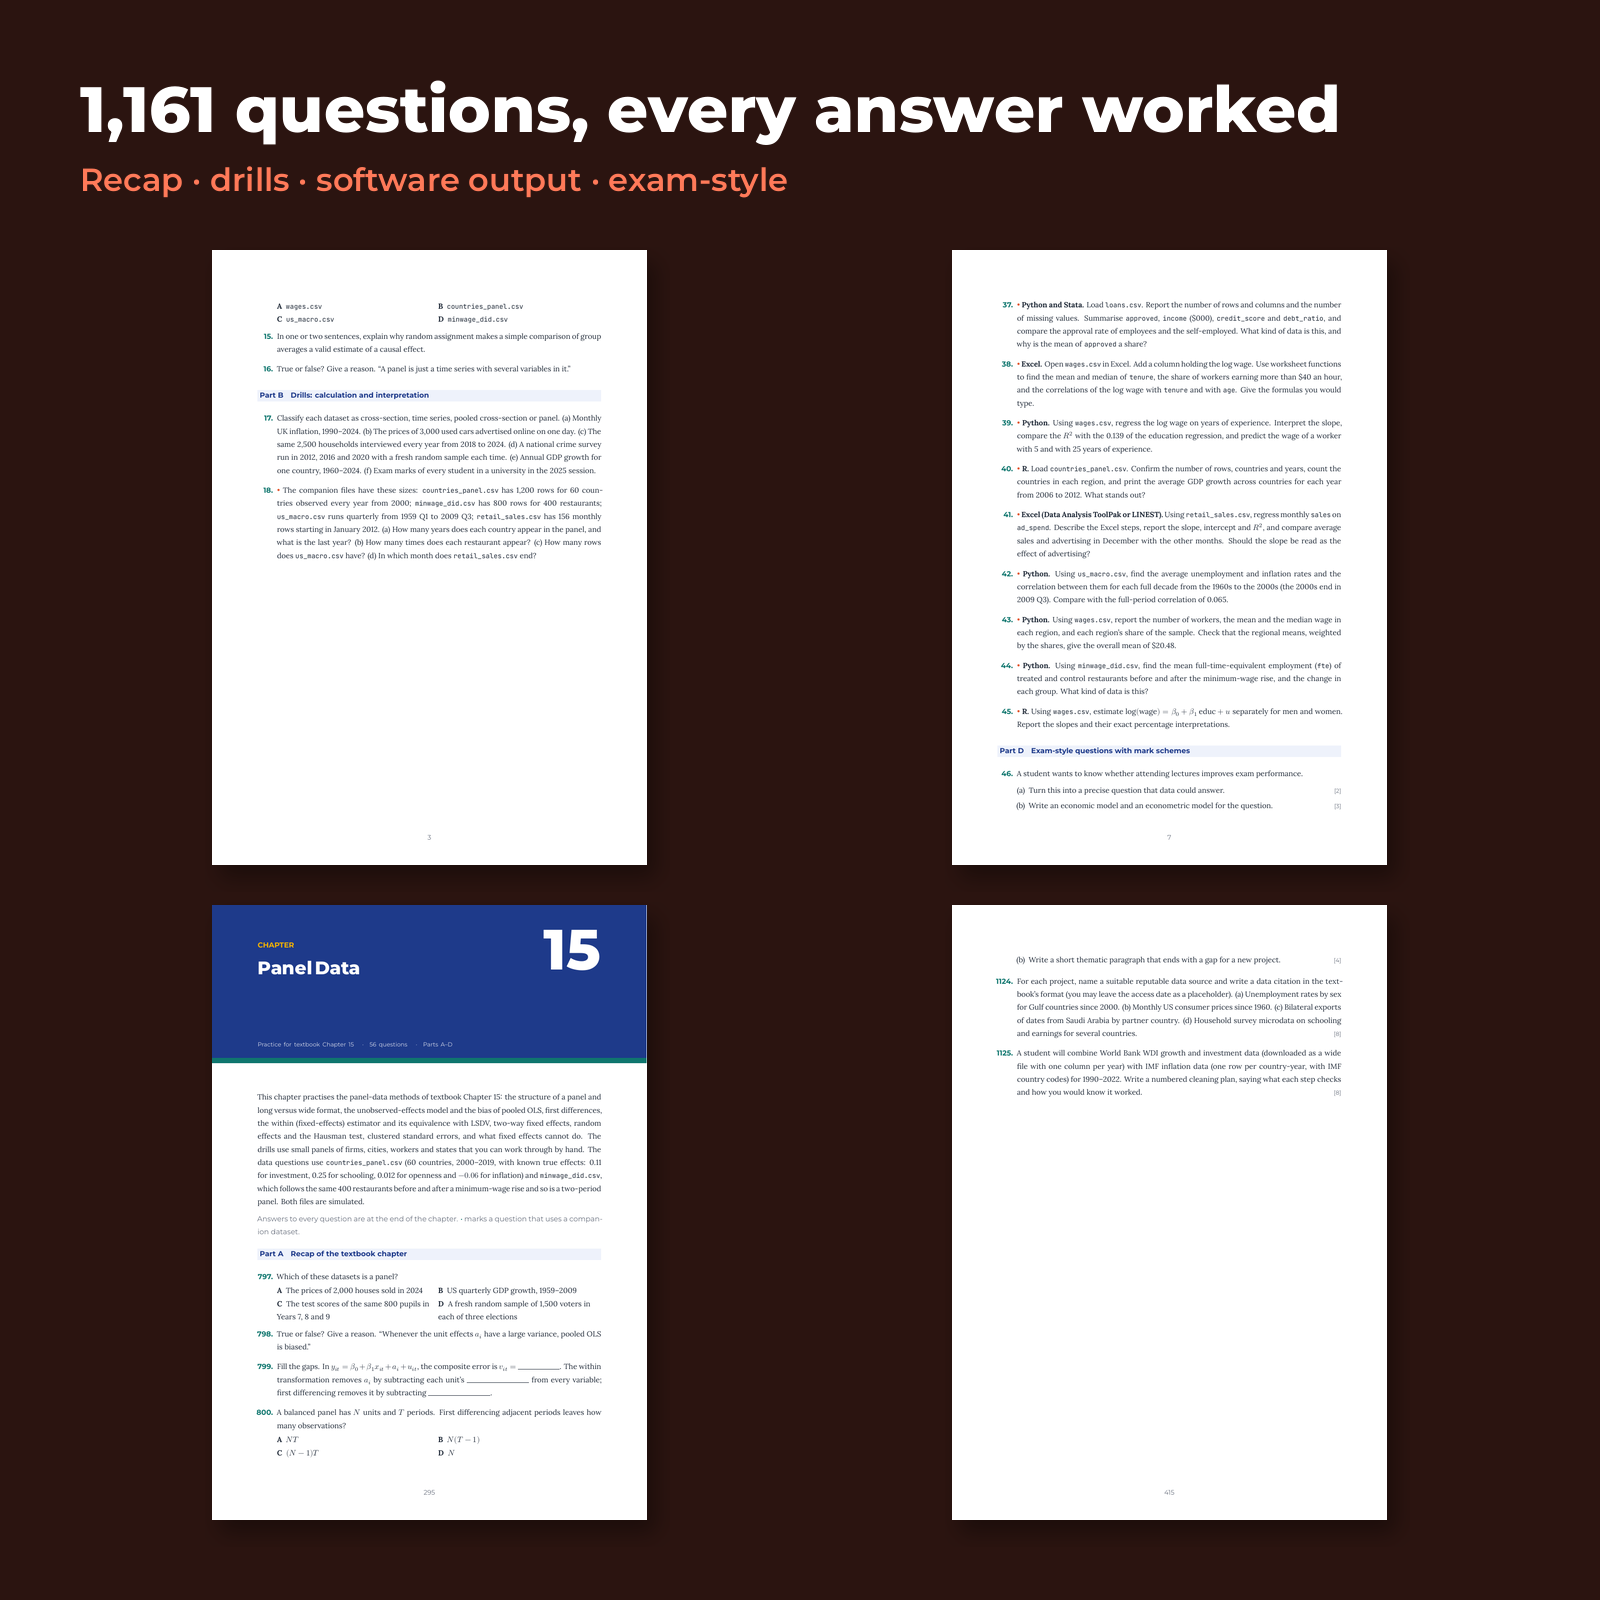
You learn econometrics by doing it. This book gives you 1,161 econometrics practice questions to do, arranged in the same 20 chapters as the Econometrics Made Simple textbook, each with a complete worked answer that shows every step, not just the final number.
How each chapter is organised
- Part A — Recap. Quick multiple-choice and true/false questions that check the ideas.
- Part B — Drills. Calculations by hand: OLS estimates, standard errors, t statistics, confidence intervals, F tests, elasticities and marginal effects.
- Part C — Software output. Real regression tables from Python, R and Stata to read and interpret: which coefficient matters, what the p-value says, whether the test rejects.
- Part D — Exam-style. Longer structured questions with marks, the kind set in university econometrics finals.
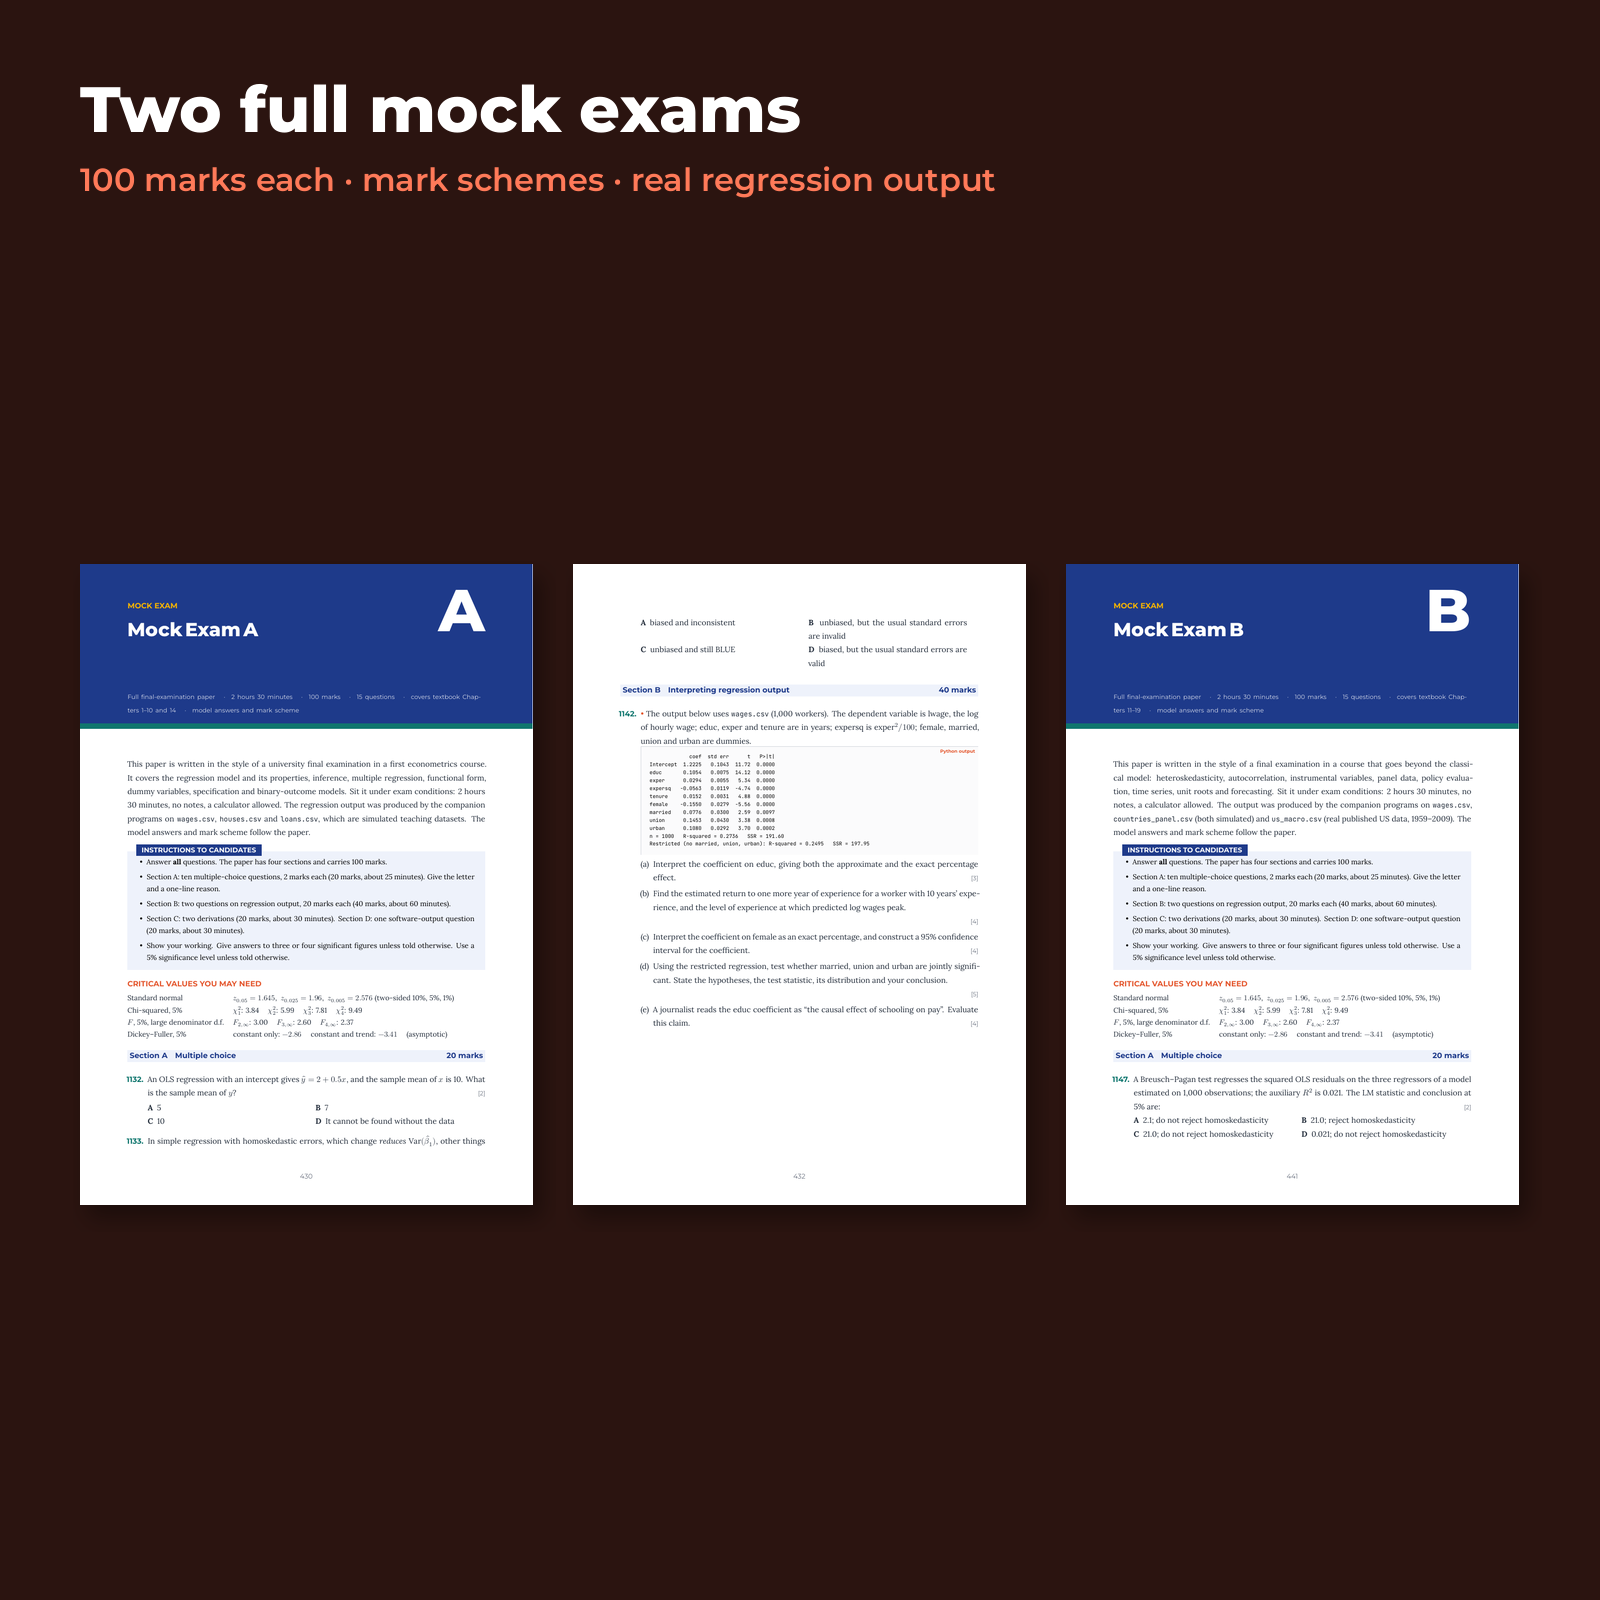
Two complete mock exams with mark schemes finish the book, so you can test yourself under timed conditions.
Topics
Probability and statistics review; simple and multiple regression; properties of OLS; hypothesis testing and confidence intervals; F tests; functional form; dummy variables and the Chow test; multicollinearity and specification; heteroskedasticity; autocorrelation and the Durbin–Watson test; instrumental variables; logit, probit and the linear probability model; fixed and random effects and the Hausman test; difference-in-differences and regression discontinuity; time-series regression; stationarity and the augmented Dickey–Fuller test; forecasting and cointegration; and empirical projects.
Every numerical answer was computed by software and checked automatically. Get it with the textbook in the Econometrics Made Simple bundle for $19.
Instant download: the full PDF plus each chapter as a separate PDF.